What are Faster Payments and Why Should a Security Practitioner Care?

summary
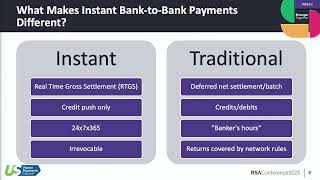
The US is introducing the first new core payment rails in 40 years: RTP is live and FedNow is coming, both using the credit push model and delivering near-instant, final funds so recovery after fraud is limited. Zelle spans ~1,000 contracted banks and ~7,000 app endpoints; RTP reaches >70% of DDAs and processes millions of transactions worth billions monthly. Fraud shifts to APP, BEC, synthetic identity and mule networks; the UK moves 2.1 trillion pounds via faster payments and adopts mitigations like the contingent reimbursement model, Confirmation of Payee and configurable accounts to slow and trace flows.
AI-written summary · about
chapters (18)
- 0:00Introduction
- 3:17What is a Faster Payment
- 4:36The US View
- 6:00The Marketplace
- 8:40Digital Payments
- 11:43Zelle Fraud
- 13:23RealTime Payments
- 15:44Business Email Compromise
- 17:53Fraud and Risk Management
- 19:21Customer Education
- 20:29Who is using Faster Payments
- 21:20How much is moved through Faster Payments
- 23:05What have they been doing
- 26:56Money laundering
- 28:53Stop people falling for scams
- 31:33How do we put this to work
- 33:34Resources
- 34:26Conclusion
related talks
 46mPayments for the 21st century and beyond
 52mThe Critical Importance of Identity for Instant Payments
 26mMastering API Platforms for Enhanced Payment Integration
 33mFinance, Money and Other Demons
 32mEnhancing Security, Reliability, and Global Scalability in FinTech
 27mDriving revenue opportunities across the Open Banking ecosystem
 59mPayments
 26mPerspectives