Governing credit scoring. Data protection, algorithms & surveillance.
summary
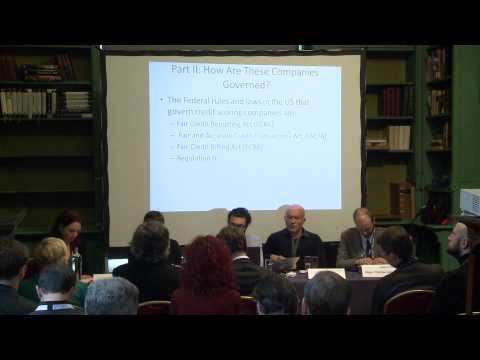
Panel reports concrete specifics: Norway requires a standard license for credit‑scoring firms that limits which sources and variables they may use and forces deletion of paid claims; US practice centers on FICO and three national CRAs with disclosed FICO scoring factors but opaque proprietary subfactors; Experian sells Mosaic lifestyle groups used to infer risk; studies show widespread inaccuracies (one research flagging ~80% of reports with errors), weak enforcement and low consumer awareness, instant scoring enabling payday lending, and proven ways some people can “play the system.”
AI-written summary · about
chapters (10)
- 0:00Start
- 25:55What is a US Credit Score?
- 29:42Who Can Access Your Credit Report
- 34:00Fair Credit Billing Act (FCBA)
- 34:43Regulation
- 36:48Subprime Lending Example
- 37:00Subprime Lending Conclusions
- 37:29Inaccuracies in Credit Reports
- 52:04What to do?
- 53:25FICO Score
related talks
 17mGetting control back
 28mGamified Control - China's Social Credit Systems
 35mDigital footprints in credit scoring
 39mHot Legal Issues
 12mInterview with – Kristina Reicher
 23mData use models and data protection
 01h 12mObscured by algorithms: how to prove "yes" if computer says "no"
 01h 16mData protection and Big Data: what about regulating Big Data analytics?