Going API First in Financial Services within Greater China
summary
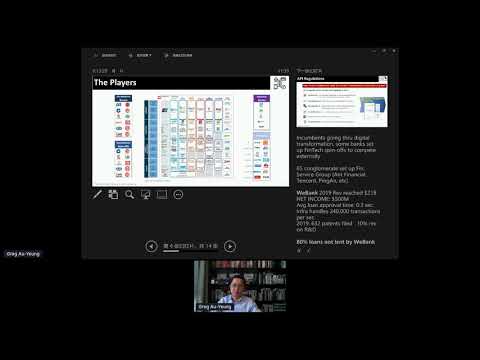
Maps China’s regulatory patchwork (FSDC, CBIRC, CSRC) to concrete API moves: Tencent’s MyBank and WeBank are internet-bank license experiments that reach profitability (industry headline: ~US$21B revenue and ~US.5B net income by 2019), major banks spin off fintech arms (OneConnect) and launch a lending cloud used by ~3–4 smaller banks, and a commercial bank AI security guideline plus imminent data/privacy laws push toward GDPR-like rules. Hong Kong already issues 8 virtual banks (6 live), but low consumer trust and crowded incumbents limit uptake.
AI-written summary · about
chapters (7)
- 0:00Intro
- 1:03Regulation in China
- 5:59Fintech in China
- 10:46API Regulation
- 12:31CRIB Lending Cloud
- 19:07Licenses
- 19:58Future Banks
related talks
 21mCapturing business value with API
 30mBanking & Open APIs
 18mOpen Banking Ecosystem – Development, Opportunities & Challenges.
 23mAboard the Beagle: New species in the banking ecosystems
 32mTransformation w. FinTech collaboration & open banking
 21mThe Open API Ecosystem
 25mOpen banking - From Efficiencies to Externalities!
 26mHow API Technology is Revolutionizing Financial Services