Beyond Open Banking - Open Innovation & Open Business

summary
Claim: open banking delivers few customer benefits because banks center products not journeys. Recommendation: create an open business line that owns partnerships, product, API development and operations so banking becomes invisible in customer journeys. Implementation relies on APIs and microservices to stitch mortgage approvals, property deposits, furniture financing and supermarket payment collaborations; examples include overnight bank–supermarket integrations. Proof points: FORMS HK is listed in Shenzhen (>6 billion RMB market cap, ~2,300 consultants) and participates in project in indra 9 rock phase 2 (CBDC).
AI-written summary · about
chapters (7)
- 0:00Introduction
- 6:41Open Banking vision
- 11:59API economy fundamentals
- 14:13Customer journeys in banking
- 17:50Open Business model
- 21:49Key takeaways
- 22:09Q&A
related talks
 25mOpen Banking is a "How" and Embedded Finance is a "Why"
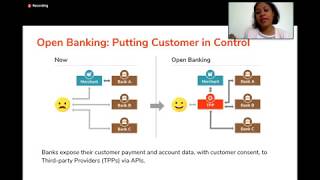 31mOpen Banking is Here to Stay: How Will You Benefit from It?
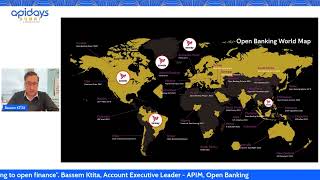 13mFrom Open Banking to Open Economy: What You Need to Know
 18mOpen Banking Ecosystem – Development, Opportunities & Challenges.
 37mIntroduction to essential elements of Open Banking Framework
 22mOpen Banking : An opportunity, not a mandate
 25mApproaches to Open Finance
 31mOpen Banking – The Brand , the Challenges and the Future