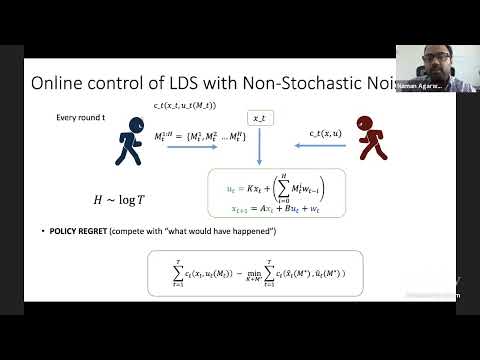
The Non-Stochastic Control Framework
summary
Provides an efficient algorithm for known, fully observed linear time invariant systems with adversarial bounded disturbances that guarantees O(√T) regret against the class of disturbance‑feedback controllers, using convexification of the control via disturbance‑feedback parameters, a mild strongly‑stable (ρ(A−BK) ≤ 1−δ) assumption, reduction to online convex optimization with memory, and an OGD‑style update with horizon H = O(log T). Implementation is polynomial in system parameters, logarithmic in time, and code is available.
AI-written summary · about
chapters (9)
- 0:00Introduction
- 3:05Optimal Control
- 11:31The Problem
- 13:27Online Control
- 18:20Reasonable Comparative Policies
- 23:14General Control
- 26:03Convexification
- 27:26Stability
- 30:39OCO with Memory
related talks
 31mLearning to Control Unknown Systems
 38mBest of Both World Algorithms from I.I.D. to Adversarial Data
 43mLearning from Dynamics
 42mA Regret Minimization Approach to Mutli-Agent Control and RL
 48mA Simple Condition for Constant Regret in Online Decision-Making
 01h 01mRobustness, Stochastics, Uncertainty 2
 01h 15mBridging Stochastic and Adversarial Bandits
 35mOnline Optimization and Learning Under Long-Term Convex Constraints and Objectives